Skip to Main Content

Asset Allocation Update: Government bonds as bodyguard

The sector rotation in October from cyclical to defensive was a statistical outlier and weighed on our positioning. However, there is little in the way of fundamental justification: technology companies are delivering strong earnings growth and the use of AI is increasing. Nevertheless, capital markets are demanding higher risk premia due to the enormous financing needs. Although we expect a countermove after the US midterms, we are slightly reducing our high exposure to the AI supply chain in view of the increased uncertainty and are using global government bonds for hedging.

Text: Roger Rüegg

Bodyguard in the portfolio: government bonds as a shield (image: iStock.com).

What adjustments have we made to the portfolios?

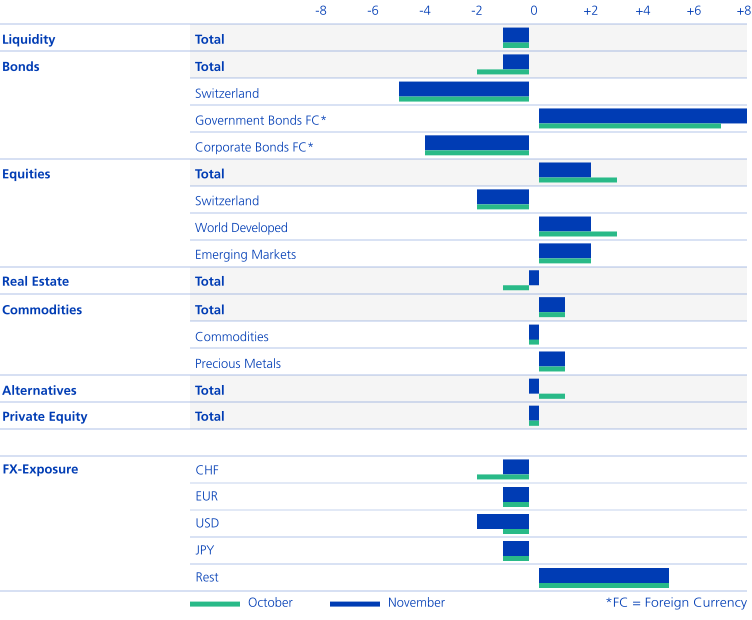
The yield on US government bonds has fallen back below 5% despite higher oil prices and strong economic data. Bonds are once again acting as a safe haven. In view of the respectable real yields, we are increasing our overweight in this asset class.

Equities remain fundamentally attractive, but the headwinds are increasing somewhat. The market reaction to corporate earnings was disappointing, which is why we are slightly reducing our overweight.

As we expect price gains in equities and bonds, we are reducing alternative investments to provide funding.

The Swiss franc is currently benefiting from political unrest in Europe and has appreciated again. We are reducing our underweight.

Bonds: Finally a safe haven again

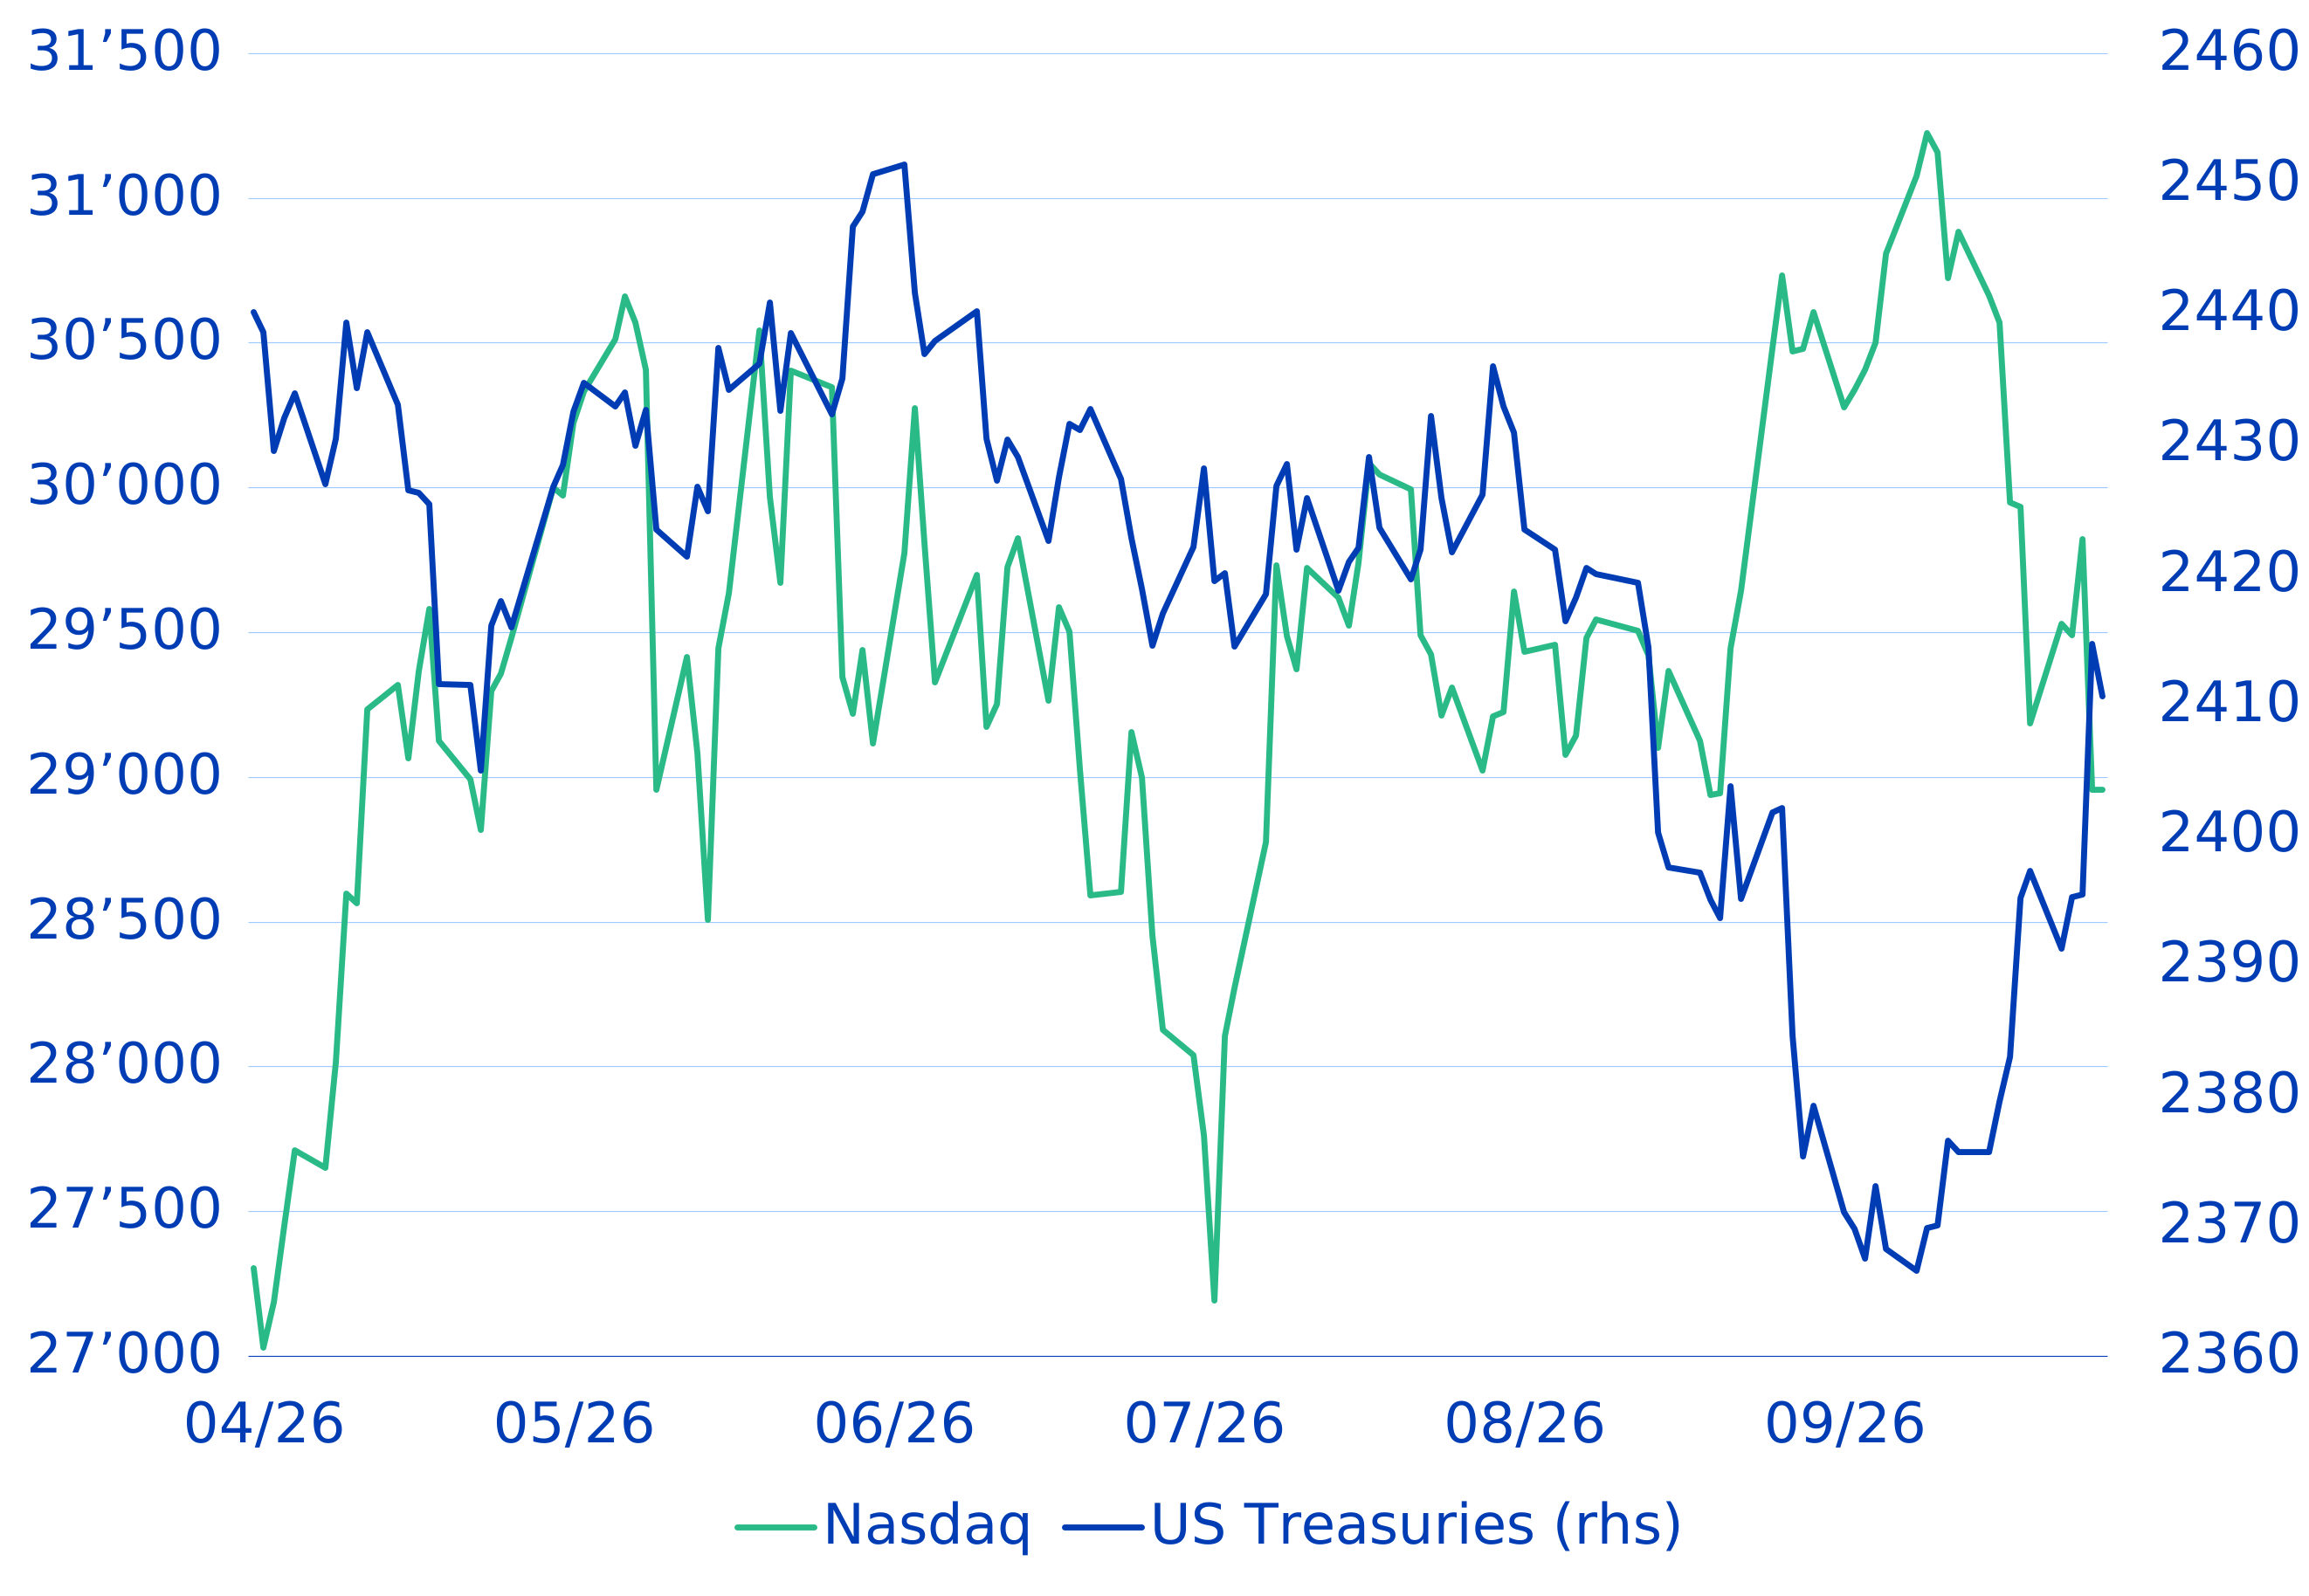
Our expected scenario for government bonds materialised in October. For some time now, we have believed that concerns about government debt and inflation are exaggerated and that government bonds are attractive at this yield level. In October, the yield on 10-year US government bonds fell back below 5% despite a renewed rise in oil prices, higher inflation figures and solid economic data. Our tactical position in long-dated US government bonds has generated a performance of 6% as a result. We are therefore increasing foreign duration once again – also as a hedge against potential further price losses in technology stocks.

Chart: Government bonds as a hedge against AI fears


Source: Bloomberg, Zürcher Kantonalbank

Equities: Sector rotation will not persist

As in July, we experienced pronounced sector rotation in October. AI-related stocks were heavily punished and many investors favoured defensive sectors. The overall market remained surprisingly robust, but beneath the surface the differences were massive: technology -7%, energy +10%, consumer staples +8%. We now expect a countermove, particularly in heavily sold off emerging-market equities. These now trade on a price/earnings ratio of below 9, making them very cheap and fundamentally significantly more attractive than Swiss equities. The relative performance difference between these two markets of 15% within three weeks is extraordinarily high in historical terms and has in the past led to strong countermoves. In return, we are reducing our overweight in global equities, as the pressure is increasing due to tighter financial conditions.

Alternative investments: Swiss real estate more attractive again

Listed Swiss real estate funds, with a loss of around 4%, are among this year’s losers. Valuations have now eased somewhat and seasonal effects are turning positive. We therefore already closed our underweight position in October and, despite isolated capital increases, expect prices to rise until year-end. In return, we have closed our overweight in alternative investments, as we now see greater price potential in traditional investments and are using these as a source of funding.

FX: Swiss franc benefits from political unrest in Europe

We continue to prefer the Australian dollar and emerging-market currencies to the euro and US dollar. For the Swiss franc, however, we are reducing our underweight, as the downward trend has been halted by political unrest in Europe and the franc is once again in demand as a safe haven.

Our Tactical Asset Allocation in November 2026


Relative weighting vs. Strategic Asset Allocation (SAA) in % in October and November 2026 (Source: Zürcher Kantonalbank, Asset Management)

Legal Notice

“BLOOMBERG®” and the Bloomberg indices listed herein (the “Indices”) are service marks of Bloomberg Finance L.P. and its affiliates, including Bloomberg Index Services Limited (“BISL”), the administrator of the Indices (collectively, “Bloomberg”) and have been licensed for use for certain purposes by the distributor hereof (the “Licensee”). Bloomberg is not affiliated with Licensee, and Bloomberg does not approve, endorse, review, or recommend the financial products named herein (the “Products”). Bloomberg does not guarantee the timeliness, accuracy, or completeness of any data or information relating to the Products.

This document is for information and advertising purposes only. It is intended for distribution in Switzerland and is not intended for investors in other countries.

It does not constitute an offer or a recommendation to purchase, hold or sell financial instruments or to obtain products or services, nor does it form the basis for a contract or an obligation of any kind.  The recip-ient is advised to review the information, possibly with the assistance of an advisor, to determine its com-patibility with their personal circumstances as well as its legal, regulatory, tax, and other implications. The information contained in this publication may be adjusted at any time.

The document was prepared by Zürcher Kantonalbank with customary due diligence and may contain information from carefully selected third-party sources. However, Zürcher Kantonalbank provides no warranty as to the correctness and completeness of the information contained therein and accepts no liability for damages resulting from the use of the document or information contained therein.

Unless otherwise stated, the information refers to Zürcher Kantonalbank's asset management under the Swisscanto brand, which primarily includes collective capital investments under Swiss, Luxembourg and Irish law (hereinafter referred to as "Swisscanto funds").

The investment opinions and assessments of securities and/or issuers contained in this document have not been prepared in accordance with the rules on the independence of financial analysts and therefore constitute marketing communications (and not independent financial analysis). In particular, the employees re-sponsible for such opinions and assessments are not necessarily subject to restrictions on trading in the relevant securities and may in principle conduct their own transactions or transactions for Zürcher Kantonalbank in these securities.

The sole binding basis for purchasing Swisscanto funds is the current fund documents (e.g. fund agreements/contractual conditions, prospectuses, key investor information or basic information sheets as well as annual reports), which can be obtained from products.swisscanto.com, Swisscanto Fund Management Company Ltd., Bahnhofstrasse 9, CH-8001 Zurich (also representative of the Luxembourg Swisscanto funds) or from all branch offices of Zürcher Kantonalbank. The paying agent for the Luxembourg Swisscanto funds in Switzerland is Zürcher Kantonalbank, Bahnhofstrasse 9, CH-8001 Zurich.

It should be noted that any information about historical performance does not indicate current or future performance, and any performance data provided may not consider the commissions and costs incurred when issuing and redeeming fund units. Any estimates regarding future returns and risks contained in the document are for informational purposes only. Zürcher Kantonalbank does not provide any guarantee for this.

Every investment involves risks, especially with regard to fluctuations in value and return.

The products and services described in this publication are not available to US persons in accordance with the applicable regulations. This publication and the information contained in it must not be distributed and/or redistributed to, used or relied upon by, any person (whether individual or entity) who may be a US person under Regulation S of the US Securities Act of 1933. US persons include any US resident; any corporation, company, partnership or other entity organized under any law of the United States; and other categories set out in Regulation S. Status of the data (unless otherwise stated): 03.2026

© 2026 Zürcher Kantonalbank. All rights reserved.

Categories

Investment Strategy